Why it matters
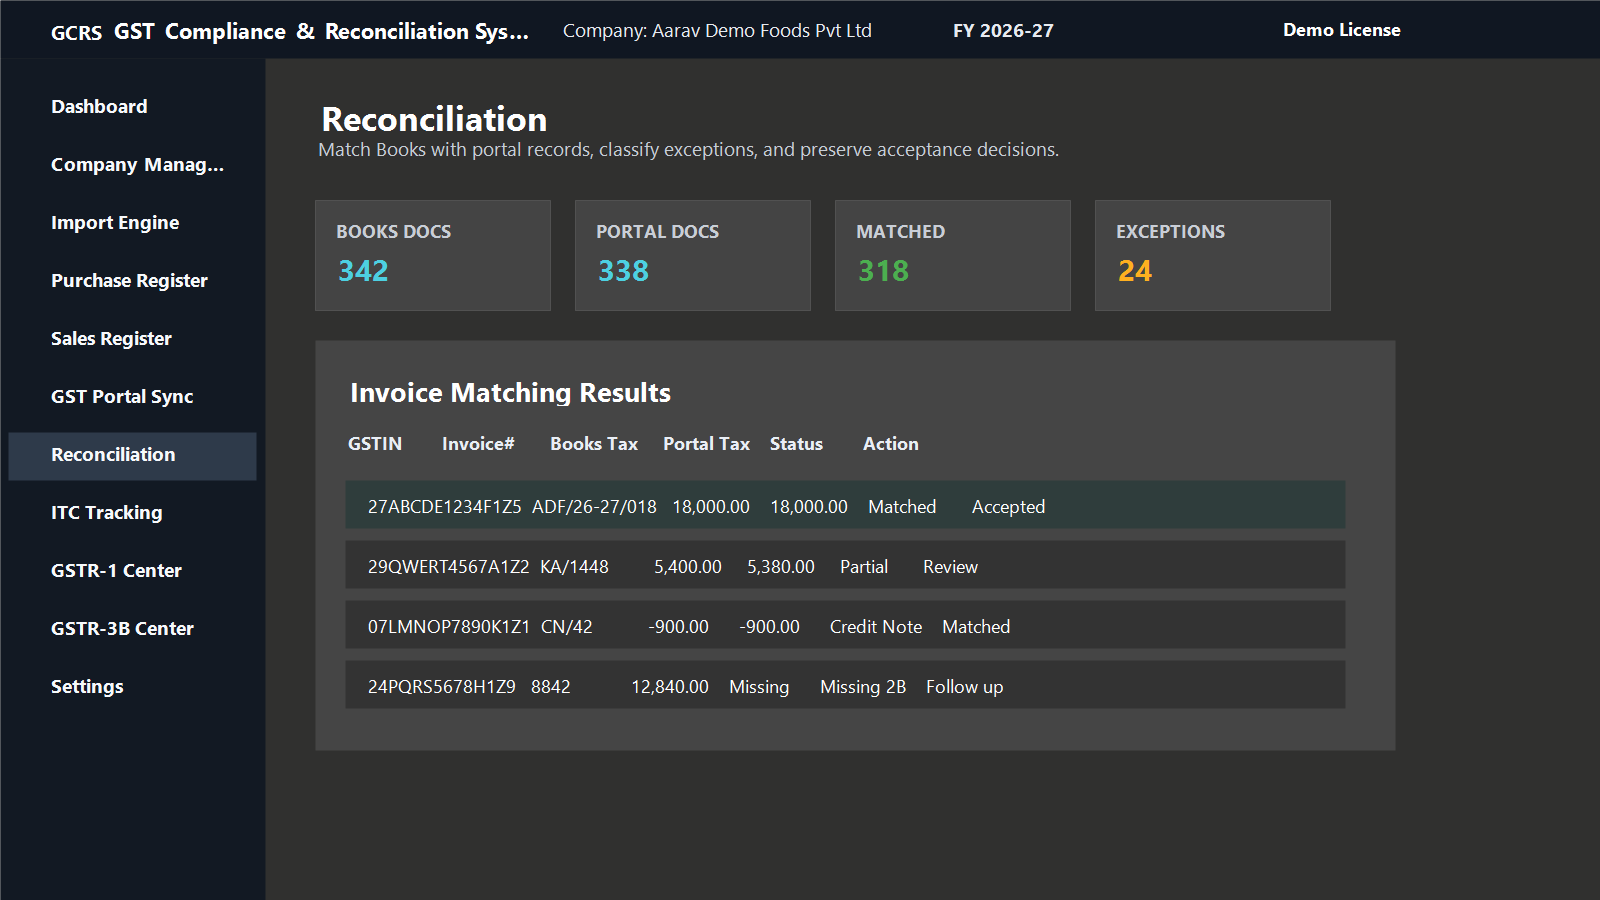
GSTR-2B is an important reference for ITC availability. If a purchase invoice is in books but not in GSTR-2B, the team should review whether ITC needs to be held, reversed, followed up with the supplier, or claimed later when reflected.
Recommended matching logic
Start with GSTIN and invoice number. Then review GSTIN, invoice number and invoice date. For difficult cases, compare GSTIN with tax amount and invoice value. Keep possible matches separate until a reviewer accepts them.
Common exception buckets
Matched invoices, missing in books, missing in GSTR-2B, tax difference, date difference, GSTIN difference, duplicate invoices, credit notes and debit notes should be reviewed separately.
Monthly review output
The final working should show books ITC, 2B ITC, matched ITC, temporary differences, permanent differences, 4B(2) reversal, 4D(1) reclaim and net eligible ITC.